
India has over 150 million demat accounts, and that number keeps climbing every quarter. Yet for every person who actually invests regularly, there are 5 or 6 who opened an account, stared at the options, and did nothing. The problem is rarely money. It is almost always confusion. Too many products, too much jargon, and too little clarity on where to start and what to do after starting.
This is the investing guide India needs, whether you are a complete beginner putting away your first 500 rupees a month or someone with a growing corpus wondering how to get smarter with it. No sales pitch, no complicated formulas. Just a clear path from your first SIP to a portfolio that can genuinely build wealth over decades.
Why Most Indians Still Keep Their Money in Savings Accounts
The default financial product in India is still the savings account. According to the Reserve Bank of India, household savings in bank deposits remain significantly higher than investments in equities or mutual funds. There is a reason for this, and it is not stupidity.
For decades, Indian families built wealth through 3 channels: fixed deposits, gold, and real estate. These were tangible, familiar, and felt safe. The stock market, on the other hand, carried a reputation shaped by scams, crashes, and stories of people losing everything. That reputation was earned in the 1990s and early 2000s, and it stuck.
What has changed is the infrastructure. The Securities and Exchange Board of India (SEBI) has tightened regulations dramatically. Mutual fund expense ratios have come down. Platforms like Zerodha, Groww, and Kuvera have made investing as simple as ordering food online. The barriers that once existed are mostly gone. What remains is a knowledge gap, and that is exactly what this guide fills.
Before You Invest a Single Rupee: The Emergency Fund
This step is boring, and it is also the most important thing you will do for your financial life. Before you open a mutual fund account, before you research stocks, before you do anything, build an emergency fund.
An emergency fund is 3 to 6 months of your essential monthly expenses, kept in a place you can access within a day. Not invested. Not locked up. Just sitting there, liquid and available. A savings account or a liquid fund works fine.
Why does this matter so much? Because life is unpredictable, and markets are volatile. If you invest without a safety net and then lose your job or face a medical emergency, you will be forced to sell your investments at exactly the wrong time, often at a loss. The emergency fund is what keeps your investment journey from being derailed by real life.
If you are already tracking how much of your income goes toward needs, wants, and savings, you are ahead of most people. For a deeper look at structuring your paycheck and deciding how much of your money should go where, that framework pairs well with everything in this guide.
Your First SIP: The Simplest Way to Start Investing
A Systematic Investment Plan, or SIP, is the single best entry point for a new investor in India. It lets you invest a fixed amount every month into a mutual fund, starting from as little as 100 or 500 rupees. You set it up once, and the money gets debited automatically from your bank account on a date you choose.
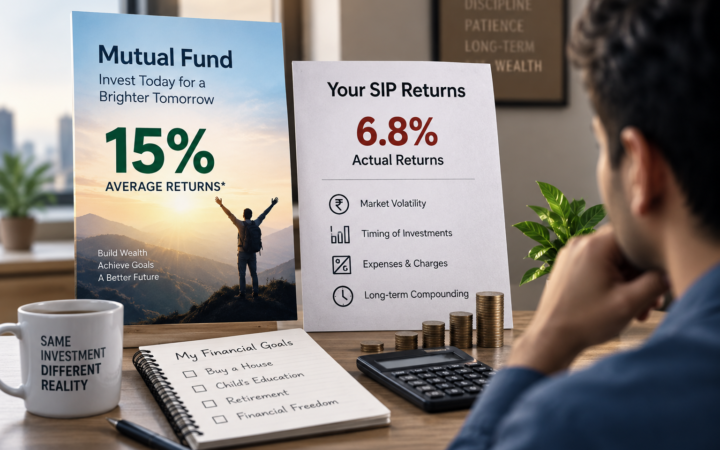
What makes SIPs powerful is not the amount. It is the discipline and the math behind it. When you invest the same amount regularly, you automatically buy more units when prices are low and fewer units when prices are high. Over time, this averages out your cost per unit. This is called rupee cost averaging, and it removes the single biggest psychological barrier to investing: the fear of buying at the wrong time.
A common question beginners ask is which mutual fund to choose for their first SIP. The straightforward answer for most people is a Nifty 50 index fund or a Nifty Next 50 index fund. These are passively managed funds that simply track the performance of the 50 or 100 largest companies listed in India. The expense ratios are low (often under 0.2%), there is no fund manager risk, and over the long term, these funds have delivered returns in the range of 12 to 14% annually before inflation.
Start with one fund. Get comfortable. Build the habit. You can diversify later.
Understanding the 3 Main Types of Mutual Funds
Once you have your first SIP running, it helps to understand the broader landscape. Mutual funds in India fall into 3 broad categories that matter for portfolio construction.
Equity funds invest in stocks. They carry higher risk but also deliver higher returns over long periods, typically 7 years or more. Within equity, you have large cap funds (stable, big companies), mid cap funds (medium sized companies with higher growth potential), small cap funds (smaller companies with the highest risk and highest reward potential), and multi cap or flexi cap funds that invest across all sizes.
Debt funds invest in bonds, government securities, and money market instruments. They are more stable than equity funds and are suitable for short to medium term goals, say 1 to 3 years. The returns are lower, usually in the range of 6 to 8%, but the ride is much smoother.
Hybrid funds mix equity and debt in a single fund. Aggressive hybrid funds typically hold around 65 to 80% in equity and the rest in debt. These can work well for moderate risk investors who want some growth without the full volatility of pure equity.
A useful mental model: equity is for goals that are 7 or more years away, debt is for goals within 3 years, and hybrid fills the space in between.
How to Pick Mutual Funds Without Overthinking It
The internet is full of mutual fund recommendations, and most of them are either outdated or driven by commissions. Here is a simpler framework that works for the majority of investors.
First, decide between direct and regular plans. Every mutual fund in India comes in 2 versions. The regular plan pays a commission to the distributor who sold it to you. The direct plan does not. Over 20 years, the difference in expense ratio between regular and direct (usually 0.5 to 1% per year) can cost you lakhs. Always choose direct plans unless you are paying a fee only advisor for their time and expertise.
Second, prioritize index funds for your core portfolio. Actively managed funds sometimes beat the index, but the data from SEBI and S&P SPIVA reports consistently shows that over 10 to 15 year periods, a majority of active large cap funds in India underperform their benchmark. Index funds remove this risk entirely.
Third, look at consistency rather than recent returns. A fund that delivered 40% last year and lost 20% the year before is far less useful than one that delivered 14 to 16% steadily. Check rolling returns over 5 and 10 year periods, not just trailing returns.
Fourth, keep it simple. For most investors, a portfolio of 2 to 4 funds is plenty. One large cap or Nifty 50 index fund, one mid cap or Nifty Next 50 index fund, and perhaps a debt fund or hybrid fund for stability. That covers most goals.
Tax-Saving Investments Every Indian Should Know
India’s income tax system offers several deductions under Section 80C of the Income Tax Act, allowing you to reduce taxable income by up to 1.5 lakh rupees per year. Many people use this section without thinking about it carefully, defaulting to insurance policies or PPF contributions. Here is a smarter way to approach it.
ELSS (Equity Linked Savings Scheme): These are mutual funds that invest in equities and come with a 3 year lock-in, the shortest among all 80C options. They offer market-linked returns (typically in line with diversified equity funds) and work well for people with a long investment horizon. The lock-in actually helps beginners by preventing panic selling.
PPF (Public Provident Fund): A government-backed savings scheme with a 15 year lock-in and a current interest rate around 7.1% (as of 2026). The returns are fully tax free, including the interest earned. PPF is excellent for the debt portion of your portfolio, offering safety that private instruments cannot match.
NPS (National Pension System): India’s retirement savings scheme allows an additional deduction of 50,000 rupees under Section 80CCD(1B), over and above the 80C limit. NPS invests your money across equity, government bonds, and corporate bonds based on the allocation you choose. The catch is that a portion of the corpus must be used to buy an annuity at retirement, and withdrawals before 60 come with restrictions.
Life insurance premiums, EPF contributions, and tuition fees also count under 80C. But buying insurance purely for tax saving is one of the most expensive mistakes Indian investors make. If you need life insurance, buy a term plan (pure protection, no investment component). Then invest separately through mutual funds. Mixing insurance and investment almost always results in poor returns and inadequate coverage.
Beyond Mutual Funds: Stocks, Gold, and Real Estate
Mutual funds are the foundation, but they are not the entire house. As your corpus grows and your knowledge deepens, other asset classes start making sense.
Direct stocks let you own shares of individual companies. The potential returns are higher than mutual funds, but so is the risk. One company can go bankrupt; a diversified mutual fund cannot. If you want to invest in individual stocks, start with companies you understand, limit direct equity to a portion of your portfolio (say 10 to 20%), and never invest money you might need within 5 years. Study financial statements, understand valuation basics, and accept that even professionals get it wrong regularly.
Gold has been a trusted store of value in India for centuries. The modern way to hold gold as an investment is through Sovereign Gold Bonds (SGBs) issued by the RBI, which offer the price appreciation of gold plus an additional 2.5% annual interest. SGBs eliminate storage costs, making charges, and purity concerns that come with physical gold. A 5 to 10% allocation to gold in your overall portfolio adds diversification, especially during periods when equity markets struggle.
Real estate is a significant asset class in India, but it behaves very differently from what most people assume. It requires large capital, comes with illiquidity, and returns vary enormously by city and micro-market. If you are evaluating whether property still makes sense as an investment in the current environment, the numbers behind real estate in 2026 tell a more nuanced story than the common narrative. For most people under 35, equity investments will compound faster and with far less friction than owning rental property.
Building Your Portfolio by Life Stage
Your investment mix should evolve as your life changes. Here is how a typical Indian investor’s portfolio might shift across different stages.
In your 20s (just starting out): You have the greatest asset any investor can have: time. Your risk tolerance is high because you have decades before you need the money. A portfolio weighted 80 to 90% toward equity (index funds plus perhaps a mid cap fund) and 10 to 20% in debt or PPF works well. The priority here is building the habit and letting compounding do its work. Even 5,000 rupees a month at 12% compounded over 30 years grows to over 1.75 crore rupees.
In your 30s (growing income, growing responsibilities): You likely have a higher salary but also bigger expenses: rent, EMIs, possibly a family. The core equity allocation stays high (70 to 80%), but you start building specific goal-based portfolios. A separate SIP for your child’s education, another for a house down payment, and a steady contribution to NPS for retirement. This is also when tax planning becomes critical, so maximize your 80C and 80CCD(1B) deductions systematically.
In your 40s (peak earning years): Your portfolio should be substantial by now if you started early. The equity allocation begins shifting toward 60 to 70%, with more flowing into debt and hybrid funds. You start thinking about wealth preservation alongside growth. Review your insurance coverage, ensure your term plan covers at least 10 to 15 times your annual income, and consider adding a health insurance top-up if your employer coverage is limited.
In your 50s and beyond (approaching retirement): The shift toward capital preservation accelerates. Equity drops to 40 to 50%, with the rest in debt funds, PPF, and senior citizen savings schemes. The focus is on building a reliable income stream. Systematic Withdrawal Plans (SWPs) from mutual funds can provide monthly income in retirement, similar to a pension but with more flexibility and often better post-tax returns.
8 Mistakes That Cost Indian Investors the Most
Knowing what to do is only half the battle. Knowing what not to do saves you more money than any single investment decision. Here are the 8 mistakes that hurt Indian investors the most.
1. Waiting for the “right time” to start. There is no perfect entry point. Markets are volatile by nature. The best time to start investing was 10 years ago. The second best time is today. Delaying a SIP by even 2 years can reduce your final corpus by 15 to 20% over a 25 year horizon.
2. Treating mutual fund SIPs like fixed deposits. Some investors start a SIP, watch the value dip below what they invested, and stop the SIP in panic. The entire point of a SIP is to keep buying through downturns. Stopping during a crash is the most expensive mistake you can make.
3. Chasing last year’s top performing fund. Performance is cyclical. The fund category that topped the charts last year often underperforms the next. Build a diversified portfolio and stick with it rather than constantly switching.
4. Ignoring expense ratios. A 1% difference in expense ratio might sound small, but over 25 years on a 50 lakh corpus, it can eat away over 12 lakh rupees. Always compare direct plan expense ratios before investing.
5. Mixing insurance and investment. ULIPs, endowment plans, and money-back policies offer poor returns and inadequate insurance. Separate the two. Buy a term plan for protection and invest the rest in mutual funds.
6. Not reviewing or rebalancing. Setting up investments and forgetting them entirely is lazy, not disciplined. Review your portfolio at least once a year. If equity has grown to 90% of your portfolio when your target was 70%, rebalance by moving some gains into debt.
7. Taking stock tips from social media. Telegram groups, YouTube channels promising 10x returns, and WhatsApp forwards are not research. They are speculation dressed as advice. If someone is giving away winning stock picks for free, ask yourself why.
8. Not accounting for inflation. A fixed deposit giving 7% sounds safe until you realize that with inflation at 5 to 6%, your real return is barely 1 to 2%. Over long periods, assets that do not beat inflation are destroying your purchasing power, not protecting it.
Advanced Strategies for the Growing Investor
Once you have the basics covered, several strategies can improve your returns and reduce risk further. These are not beginner moves, but they are well within reach for anyone who has been investing consistently for 3 to 5 years.
Factor-based investing: Instead of investing in a plain vanilla index, factor funds target specific characteristics linked to higher returns, such as value (underpriced stocks), momentum (stocks trending upward), or quality (companies with strong balance sheets). In India, Nifty 200 Momentum 30 and Nifty Alpha Low Volatility 30 are examples of factor indices with dedicated index funds.
International diversification: India is one of the fastest growing large economies, and the real story behind India’s GDP growth in 2026 is encouraging. But concentrating all your wealth in a single country exposes you to currency risk, regulatory risk, and market cycle risk. Allocating 10 to 15% of your equity portfolio to international funds, particularly a US S&P 500 index fund or a global index fund, adds a layer of diversification that smooths out your overall returns.
Goal-based investing: Instead of investing into a single pot, create separate portfolios for each financial goal. Your retirement corpus goes into a high equity allocation SIP with a 25 year horizon. Your child’s college fund goes into a balanced approach with a 15 year timeline. Your car purchase in 3 years goes into a short duration debt fund. This approach ensures each goal is funded with the right level of risk.
Tax loss harvesting: If a portion of your portfolio is in loss, you can sell those investments, book the loss, and set it off against capital gains from profitable investments. This reduces your tax liability without meaningfully changing your portfolio, especially if you reinvest into a similar (but not identical) fund. In India, short term capital gains on equity are taxed at 20%, and long term gains above 1.25 lakh rupees per year are taxed at 12.5%. Smart harvesting can save you a meaningful amount over a lifetime.
The Mindset That Separates Wealth Builders From Everyone Else
The technical knowledge matters, but the real differentiator is behavior. The investors who build lasting wealth in India are not the smartest people in the room. They are the most consistent.
They start early, even with small amounts. They do not stop SIPs during market crashes. They ignore daily market noise. They review their portfolios once or twice a year, not once a day. They understand that wealth building is boring by design, and they are okay with that.
India’s economic trajectory is one of the most promising in the world right now. Rising incomes, a young workforce, digital infrastructure, and a growing consumer base all create a strong tailwind for long term investors. But the tailwind only helps if you are in the game.
You do not need a finance degree or a large salary to build wealth in India. You need a clear plan, the discipline to follow it, and the patience to let compounding do what it does best. The roadmap is in front of you. The first step is the SIP you start this month.